Surrounding Yourself with Positive People

The Power of Evolving Beliefs in Guiding Multi-Generational Wealth

Surrounding Yourself with Positive People

The Power of Evolving Beliefs in Guiding Multi-Generational Wealth

“We are made wise not by the recollection of our past, but by the responsibility for our future.”

~ George Bernard Shaw

Every family carries stories that shape how they work, decide, and understand themselves. Some are spoken often; others sit quietly in the background, influencing choices without being named. Over time, these beliefs become familiar, part of the fabric of how the family operates.

It is important to honour these stories. They hold history, meaning, and the intentions of those who came before us. But there is also value in revisiting them. As families grow and circumstances change, even long-standing beliefs can benefit from a fresh look. At times, a straightforward inquiry can provide valuable insights. Does this philosophy still serve us? This process can provide clarity, alignment, and a more intentional path forward.

The Subtle Manifestation of Inherited Beliefs

Inherited beliefs often surface in subtle ways. A familiar phrase returns during a discussion. A hesitation appears when a new idea is introduced. A decision feels “natural” simply because it’s how the family has always done it. Over time, these patterns create an internal guide, one that feels safe, familiar, and connected to the family’s identity.

You can see these influences in how families handle money, responsibility, and change. Someone may rely on an approach that once created stability, while another avoids certain conversations because openness was never encouraged. These responses are rarely deliberate; they come from experiences that settled in quietly and were never revisited.

Across generations, these beliefs shape how opportunities are interpreted, how confident someone feels stepping into a role, and what the family sees as possible. Even unspoken, they influence decisions day to day.

Many families recognize themselves in beliefs like:

● “We don’t talk about money in this family.”

● “If they know what they’ll inherit, they’ll lose motivation.”

● “You can’t trust outsiders with financial decisions.”

● “Spending on yourself is indulgent; you have to earn enjoyment.”

● “If I can’t see it or control it, it isn’t safe.”

Individually, these ideas may seem small. Together, they create a framework that shapes behaviour until the family pauses to ask whether their beliefs still support where they want to go.

Why These Beliefs Stay And How Families Move Forward

Many beliefs endure because they once offered comfort or stability. Even as circumstances evolve, familiar ideas can feel safe, and over time they become woven into a family’s identity.

This is where the distinction between meaning and current relevance matters. A belief may feel true because it once played an important role, even if it no longer reflects what the family needs today.

When families revisit these long-held ideas, the intention isn’t to label them as right or wrong. Instead, it’s to pause and ask a simple, grounding question:

“Does this philosophy still serve us now?”

This approach honours the past while creating spaces for clarity in the present. Some beliefs continue to offer guidance. Others might have already achieved their purpose, and acknowledging their accomplishment paves the way for healthier, more purposeful decisions in the future.

Closing Thoughts

When families begin to look at long-held beliefs with care, a gentle moment of perspective often emerges, one that allows them to see where the belief came from, what it once protected, and whether it still supports the direction they hope to take.

Clarity often begins in that quiet space. When a belief is seen with fresh eyes, it becomes easier to recognize what should continue, what might need to evolve, and what has simply fulfilled its purpose. The past isn’t dismissed; it’s acknowledged and carried forward in a form that fits the life the family is shaping now.

Beliefs that once felt fixed become part of an unfolding story. And many families find reassurance in knowing they don’t need to resolve everything at once.

If your family is exploring these themes in your own way, we’d be glad to walk alongside you whenever the time feels right. You are welcome to schedule a conversation here.
DISCLAIMER:
 
Cory Gagnon is a Senior Wealth Advisor with Assante Financial Management Ltd. The opinions expressed are those of the author and not necessarily those of Assante Financial Management Ltd. Please contact him at 403 232 8378 or visit https://beaconfamilyoffice.com/ to discuss your particular circumstances prior to acting on the information above. This material is provided for general information, and the opinions expressed and information provided herein are subject to change without notice. Every effort has been made to compile this material from reliable sources; however, no warranty can be made as to its accuracy or completeness. Before acting on the information presented, please seek professional financial advice based on your personal circumstances.
Picture of ABOUT THE AUTHOR

ABOUT THE AUTHOR

As the Senior Wealth Advisor at Beacon Family Office at Assante, Cory Gagnon has supported successful family enterprises to preserve, protect and transition their wealth since 2011.

Cory’s personal objective as a Wealth Advisor is simple. He is committed to supporting families to take control of the areas of their lives that truly matter to them. This commitment revolves around using specific tools and strategies that enable families to take action with confidence which will support them through life’s critical transitions.
Picture of ABOUT THE AUTHOR

ABOUT THE AUTHOR

As the Senior Wealth Advisor at Beacon Family Office at Assante, Cory Gagnon has supported successful family enterprises to preserve, protect and transition their wealth since 2011.

Cory’s personal objective as a Wealth Advisor is simple. He is committed to supporting families to take control of the areas of their lives that truly matter to them. This commitment revolves around using specific tools and strategies that enable families to take action with confidence which will support them through life’s critical transitions.
Share this post:

Facebook
Twitter
LinkedIn

KEEP READING?

2025 Week 52

Cathedral Thinking and the Work That Continues Beyond Us

Cathedral Thinking and the Work That Continues Beyond Us

“What we do now echoes in eternity.”
~ Marcus Aurelius
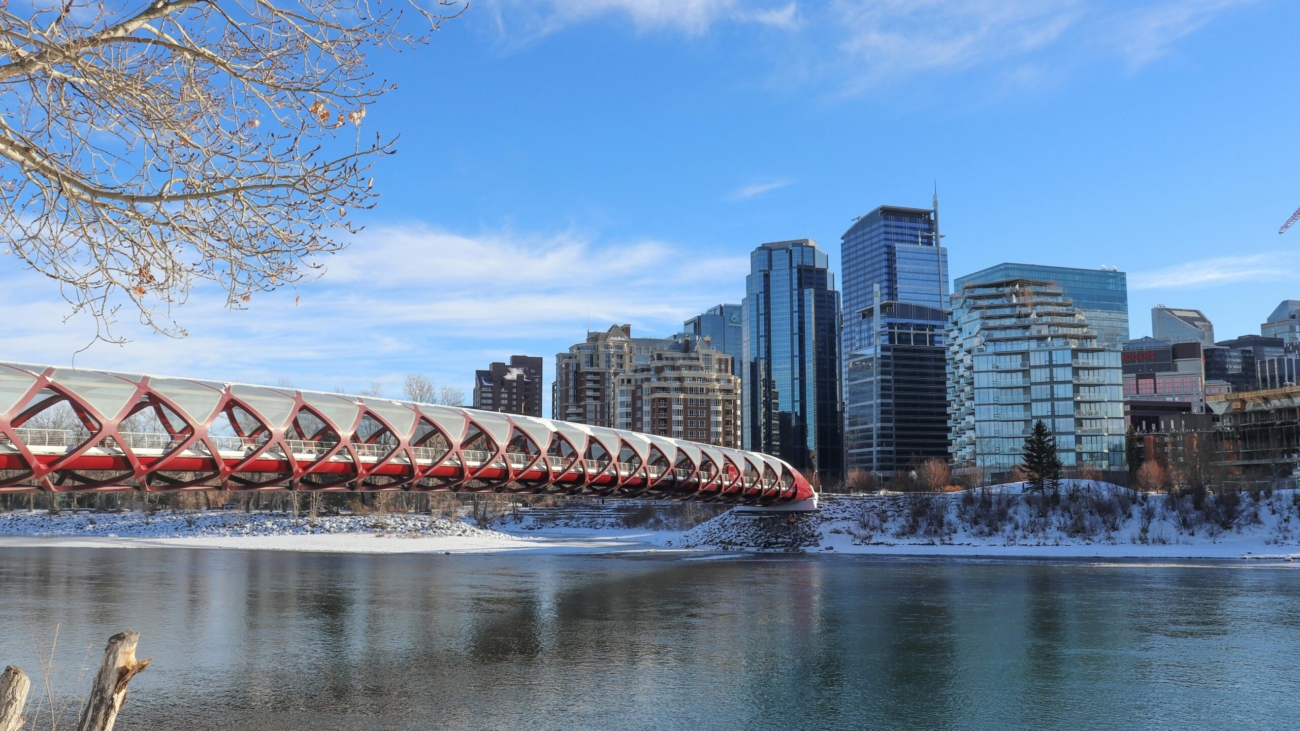
If you walk along the Bow River near downtown Calgary, you will eventually come across the Peace Bridge. The bridge is unquestionably beautiful, but what’s even more amazing is how well it has been maintained. Workers repaint the metal, reinforce weak areas, and repair weather-damaged elements. People walk and ride their bikes without much attention. Thousands of people use the bridge daily, necessitating constant maintenance.
 
This picture came to mind while I was talking to Julia Chung on Episode 52 of our Legacy Builders Podcast. She talked about a concept called Cathedral Thinking. It refers to work that carries on across many years, often longer than a single lifetime. An initial group initiates the process, subsequent groups maintain it, and further groups will assume responsibility in due course.
 
People often mention the Sagrada Familia in Barcelona in this context. Construction began in the late 1800s and continues to this day. The original designers knew the work would outlast them. They did their part, and others followed. The meaning did not depend on seeing the finished result.
 
Family enterprises often develop in a similar way. Something begins in one generation and continues through many hands and seasons of life.

Tracing the Roots of Our Decisions

Families pass down more than businesses or property. They inherit ways of collaborating, making decisions, communicating, and interpreting values, patterns often absorbed through observation rather than written rules.
 
Urgency or circumstance frequently shapes choices in the early stages of an enterprise. Over time, these adaptive habits become part of the family narrative, even when their origins are forgotten.
 
Understanding this history is grounding. It helps the current generation see what they are truly inheriting and discern what deserves to be carried forward versus what simply evolved from an earlier moment.

The Work of the Present Generation

The current generation carries a unique responsibility. They are close enough to understand the intentions that shaped the enterprise, yet they operate in a world that looks very different; markets, communication, expectations, and pace have all evolved.
Their task is usually one of thoughtful adjustment rather than dramatic change. It may involve careful conversations, revisiting old agreements, clarifying long-held assumptions, or adapting practices to fit today’s realities.
 
This work unfolds slowly, around board tables, at kitchen counters, in quiet moments after family meetings, or on walks by the river. The pace may seem modest, but this is where continuity lives. Progress comes through small shifts and attentive listening.
The aim is not to resolve everything at once but to keep the enterprise grounded, functional, and aligned with the present moment.

Making Space for Those Who Come Next

At some point, another generation will stand where the current one stands. They will inherit both the visible and invisible parts of the enterprise. Their experience will be shaped by how clear, accessible, and supportive the foundations are.
 
Cathedral Thinking invites a gentle question:
 
What can be made easier for those who will eventually take responsibility?
 
This does not require predicting the future. It involves making room for others to learn and form their understanding. It may include writing down the story of how the enterprise began and why certain decisions were meaningful. It may involve creating ways for younger family members to observe leadership before they are expected to participate in it. It may also involve simplifying structures so decision-making is less burdensome.
 
The point is to release control and avoid designing the future for others. It is to allow the next generation to enter with clarity instead of confusion.

The Quiet Work

Much of what sustains a family enterprise happens quietly. It’s the steady tending of relationships, the patience to hear differing views, the willingness to revisit unresolved conversations, and the commitment to share knowledge rather than hold it.
 
This work is a bit like the ongoing maintenance of the Peace Bridge. People only notice it when it’s neglected. Consistent care may draw little attention, but it’s felt in the ease of every crossing.
Families who embrace this kind of steady effort often find that progress builds over time in small, nearly invisible steps that add up to meaningful continuity.

Closing Thoughts

Cathedral Thinking is about putting in consistent, deliberate work over time, becoming a part of a story that’s already underway, doing our part, and having faith that other people will carry on the work in their own unique ways.
 
“We don’t have to finish the structure; we just have to add our part carefully.”
 
In family businesses, that contribution often looks like being there, paying attention, being clear, and listening. It may not be public, but those who follow it feel it, and that’s where a lot of the meaning is.

These conversations usually begin quietly, often with a simple moment of recognition. If you’d like room to explore what this means for your family enterprise, Beacon Family Office is here to support thoughtful, forward-looking dialogue. Schedule a conversation when you’re ready.

DISCLAIMER:
 
Cory Gagnon is a Senior Wealth Advisor with Assante Financial Management Ltd. The opinions expressed are those of the author and not necessarily those of Assante Financial Management Ltd. Please contact him at 403 232 8378 or visit https://beaconfamilyoffice.com/ to discuss your particular circumstances prior to acting on the information above. This material is provided for general information, and the opinions expressed and information provided herein are subject to change without notice. Every effort has been made to compile this material from reliable sources; however, no warranty can be made as to its accuracy or completeness. Before acting on the information presented, please seek professional financial advice based on your personal circumstances.
Picture of ABOUT THE AUTHOR

ABOUT THE AUTHOR

As the Senior Wealth Advisor at Beacon Family Office at Assante, Cory Gagnon has supported successful family enterprises to preserve, protect and transition their wealth since 2011.

Cory’s personal objective as a Wealth Advisor is simple. He is committed to supporting families to take control of the areas of their lives that truly matter to them. This commitment revolves around using specific tools and strategies that enable families to take action with confidence which will support them through life’s critical transitions.
Picture of ABOUT THE AUTHOR

ABOUT THE AUTHOR

As the Senior Wealth Advisor at Beacon Family Office at Assante, Cory Gagnon has supported successful family enterprises to preserve, protect and transition their wealth since 2011.

Cory’s personal objective as a Wealth Advisor is simple. He is committed to supporting families to take control of the areas of their lives that truly matter to them. This commitment revolves around using specific tools and strategies that enable families to take action with confidence which will support them through life’s critical transitions.
Share this post:

Facebook
Twitter
LinkedIn

KEEP READING?

pexels-zlataky-cz-61823415-8442351

From Scarcity to Stewardship: Guiding the Emotional Transition of Inherited Wealth

From Scarcity to Stewardship: Guiding the Emotional Transition of Inherited Wealth

“Inherited wealth is a responsibility, not just a reward. How you handle it defines its legacy.”
~ Unknown
 
Humans are wired for stability. Our bodies regulate temperature within half a degree, our hearts regulate their rhythm, and our cells seek equilibrium, a drive called homeostasis. This instinct extends to our emotions, habits, and even our relationship with wealth.
 
Sudden change can feel unsettling. For someone who might have spent the majority of their life making every dollar count, sudden wealth can feel as foreign as a tropical climate feels to someone raised in the Arctic. Viewed through the lens of homeostasis, though, these reactions are not irrational but perhaps attempts to restore safety, thus offering families a framework to navigate newfound wealth with intention and awareness.

How People Respond to Sudden Wealth

In my work with families and inheritors, one thing is clear: people don’t react to sudden wealth in one predictable way. Each response is shaped by lived experience and by the nervous system’s pull toward what feels safe and familiar. Recognizing these patterns is not about judgment; it’s about understanding.
 
Over time, I’ve seen these reactions cluster into three broad but beneficial themes.
 
The Saver
Some people hold tightly to their money because visibility feels safer than growth. What looks cautious from the outside is often simply a way to steady the ground beneath them.
 
The Giver or Spender
Others let wealth go quickly, through gifts, donations, or rapid spending, because abundance feels unfamiliar. Releasing money becomes a way to ease the tension between past and present.
 
The Worker
And some kept moving. Even with more than enough, they continue building and striving because work has long been their anchor. Slowing down can feel like losing a part of oneself.
 
When people begin to see their pattern, something shifts. The overwhelm softens. New questions emerge, gentle, curious ones:
 
What matters to me now?
What do I want this chapter to feel like?
 
There is no right pace. Whether someone moves quickly or takes time to adjust, each path is simply a way of finding safety in a changed life.

What Would Make This Change Feel More Adaptable?

In my work with families, I’ve found a few conditions that reliably support this transition:
 
● A supportive space to talk about the emotional side of wealth
● Room to reflect on personal history without being defined by it
● Small, low-risk decisions that build confidence
● Relationships that encourage patience, curiosity, and comfort with uncertainty
 
These elements help people find steadiness from within. As that internal footing strengthens, choices feel lighter, clarity comes more naturally, and the path forward begins to take shape with greater ease.

Closing Thoughts

If you recognize yourself in these patterns, it may help to know how common they are. Many people move through this transition quietly, unsure whether their reactions are “right.” And if someone you care about is navigating it, understanding these emotional dynamics can make it easier to offer patience, empathy, and steadiness. Often, a calm presence or a thoughtful question does far more than we realize.

If you’d like to explore these questions for yourself, your family, or someone you support, you’re welcome to reach out. Schedule a conversation. We’d be glad to sit with you, listen, and consider what this transition could look like in real life.

Picture of ABOUT THE AUTHOR

ABOUT THE AUTHOR

As the Senior Wealth Advisor at Beacon Family Office at Assante, Cory Gagnon has supported successful family enterprises to preserve, protect and transition their wealth since 2011.

Cory’s personal objective as a Wealth Advisor is simple. He is committed to supporting families to take control of the areas of their lives that truly matter to them. This commitment revolves around using specific tools and strategies that enable families to take action with confidence which will support them through life’s critical transitions.
Picture of ABOUT THE AUTHOR

ABOUT THE AUTHOR

As the Senior Wealth Advisor at Beacon Family Office at Assante, Cory Gagnon has supported successful family enterprises to preserve, protect and transition their wealth since 2011.

Cory’s personal objective as a Wealth Advisor is simple. He is committed to supporting families to take control of the areas of their lives that truly matter to them. This commitment revolves around using specific tools and strategies that enable families to take action with confidence which will support them through life’s critical transitions.
Share this post:

Facebook
Twitter
LinkedIn

KEEP READING?

2025 Week 48

Intentional Giving, Enduring Family Impact

Intentional Giving, Enduring Family Impact

Philanthropy is no longer an afterthought in estate planning for ultra-wealthy families; it has become a central pillar, reflecting both tax strategy and evolving family values. Charitable giving is now integrated into succession plans and family governance, shaping how wealth is passed down and used.
 
Globally, nearly 1 in 5 ultra-high-net-worth individuals has established a private foundation, rising to almost 30% among those with fortunes over $100 million. In Canada, donor-advised funds (DAFs) and private foundations have grown alongside expanding wealth. As one UK wealth report observed, “Philanthropy has been rising up the agenda for many clients, supported by a new generation. During a major intergenerational transfer of wealth, many younger heirs proactively raise charitable giving as one of the first issues.” Today’s inheritors want their wealth to do good, and they are ensuring estate plans make that possible.
 
With an expanding array of philanthropic tools available, families now have more ways than ever to align giving with their values and create lasting, meaningful impact.

Philanthropic Tools for Lasting Legacy

  1. Donor-Advised Funds: A Popular Vehicle
One of the most popular tools is the Donor-Advised Fund (DAF). A DAF allows donors to make a charitable contribution and receive immediate tax relief while delaying the decision about which charities will ultimately benefit.
 
DAFs have grown rapidly as an alternative to standalone family foundations. Their appeal lies in:

● Flexibility: Families can take time to decide how to best allocate their giving.

● Administrative simplicity: DAFs spare donors the burden of managing a private charity.

● Privacy: Families can choose to give anonymously if they wish.

●  Strategic planning: DAFs make it easy to commit to multi-year grants without creating complex governance structures.

In Canada, both the number of DAF accounts and the assets they hold have risen steadily, reflecting this global trend of “charitable savings accounts” becoming mainstream in wealth planning.
 
2. Private Foundations
 
For families with substantial resources and a desire for a durable public or family-facing presence, private foundations remain a go-to structure. The Weston Family Foundation is one example: in 2023 it had assets of $424 million and made $61.8 million in disbursements. 
However, foundations in Canada must meet a disbursement quota, a requirement that they spend a percentage of their assets each year for charitable purposes.
 
3. Bequests & Lifetime Giving
 
Many families combine lifetime giving with charitable dispositions through their will. Estate planners in Canada often include bequests, designate charities as beneficiaries of RRSPs/RRIFs, or set up charitable trusts. These strategies enable families to take advantage of tax efficiency and guarantee the honour of their charitable intentions after their deaths.
 
When integrated well, these tools allow estate plans to rise above “asset transfers” and become platforms for values, impact, and intergenerational purpose.

Shifting Philosophy of Giving

Beyond the structures, the philosophy of giving itself is evolving. Many UHNW families are taking a more strategic, outcome-focused approach. Family offices increasingly employ philanthropy advisors and impact investment specialists to ensure that donations generate measurable results.
 
Next-generation philanthropists in particular are demanding metrics, transparency, and accountability. As a result, estate plans are beginning to embed charitable objectives directly in governance documents. For example, some family trusts require annual charitable contributions or include provisions to encourage heirs to carry forward the founders’ vision.
 
Lifetime giving is also on the rise. By making significant donations during their lifetimes, wealth holders can both reduce the taxable value of their estates and experience the joy of seeing their philanthropy at work.

Preparing the Next Generation

Philanthropy is also becoming a tool for family engagement and education. Many Canadian UHNW families invite younger members to serve on the boards of their family foundations or oversee specific grantmaking programs. These roles provide both apprenticeship in stewardship and a sense of shared purpose.
 
By involving the rising generation, families prepare heirs for larger responsibilities while reinforcing the values that underlie their wealth.

Closing Thoughts

When Canadians think about estate planning, the conversation often stops at taxes, trusts, and inheritances. But beneath the numbers is a harder question: what do we want this wealth to say about us when we’re no longer here?
 
As you consider your planning, ask yourself: What do I want the next generation to learn about responsibility and generosity from the way my estate is designed? Will they see wealth as something to protect only for themselves or as a tool to strengthen the world around them? These are not easy questions, but they are the ones that turn estate planning into legacy planning.

If these questions are ones your family is beginning to ask, we’d be honoured to explore them with you. Connect with us to explore how thoughtful planning can align your estate with the legacy you want to leave behind.

DISCLAIMER:
 
Cory Gagnon is a Senior Wealth Advisor with Assante Financial Management Ltd. The opinions expressed are those of the author and not necessarily those of Assante Financial Management Ltd. Please contact him at 403 232 8378 or visit https://beaconfamilyoffice.com/ to discuss your particular circumstances prior to acting on the information above. This material is provided for general information, and the opinions expressed and information provided herein are subject to change without notice. Every effort has been made to compile this material from reliable sources; however, no warranty can be made as to its accuracy or completeness. Before acting on the information presented, please seek professional financial advice based on your personal circumstances.
Picture of ABOUT THE AUTHOR

ABOUT THE AUTHOR

As the Senior Wealth Advisor at Beacon Family Office at Assante, Cory Gagnon has supported successful family enterprises to preserve, protect and transition their wealth since 2011.

Cory’s personal objective as a Wealth Advisor is simple. He is committed to supporting families to take control of the areas of their lives that truly matter to them. This commitment revolves around using specific tools and strategies that enable families to take action with confidence which will support them through life’s critical transitions.

Share this post:

Facebook
Twitter
LinkedIn

KEEP READING?

2025 Week 46

Reimagining the Bequest: How Families Can Shape Social Capital

Reimagining the Bequest: How Families Can Shape Social Capital

Many Canadian families already make charitable gifts through their estates; the real question is whether those gifts will happen by default or by design.
 
Recently, I met with a couple reviewing their estate plan. As we walked through the details, I pointed out an unintentional $1 million “bequest.” They were puzzled until I explained that, upon their passing, the Canada Revenue Agency would receive that amount in taxes. Like many families, they were surprised to realize that their taxes at death represent a form of social capital, one that can be thoughtfully directed rather than left to chance.

Social Capital: The Hidden Asset

Every Canadian family with significant wealth has a form of social capital: funds that will ultimately leave the estate through taxes. The real question is whether the family is intentionally directing those funds.
 
Consider this: Canada’s charitable tax rules are among the most generous in the world. Gifts to registered charities generate tax credits that can offset estate taxes. In practical terms, a $2 charitable donation can eliminate roughly $1 of tax, like a built-in government match.
 
Here’s how it works in practice. A family with three children expects each to inherit $4 million, with a $1.5 million estate tax bill looming. Rather than simply paying that tax, the family could redirect it. If each child agreed to receive $500,000 less, the pooled $1.5 million could become a $3 million charitable fund, fully eliminating the tax and giving the family a lasting philanthropic legacy they control together.
 
The key: this choice must be made when the wills are drafted, not after the estate is being administered. By exercising foresight, families can convert potential tax losses into a significant, targeted influence.

Turning Taxes into Impact: How Families Can Unlock Their Bequest

Many Canadians overlook a powerful opportunity: the portion of their estate going to taxes can become a meaningful charitable gift.
 
Know your options: Taxes don’t have to be automatic; they can be directed intentionally.
 
Start the conversation: Open discussions about wealth and legacy create clarity and choice.
 
Think big: The largest “inheritance” isn’t always what goes to children; it can be the impact you leave through giving.
 
Simplify planning: Charitable strategies are accessible for families of all sizes.
 
Shift perspective: See taxes as a tool for intentional giving, not just an obligation.
 
Take your time: Charities can be chosen thoughtfully, over time, not all at once.

Turning Conversations Into Action

These choices should be made during planning, not after death, when emotions are high and options are limited. This is where a facilitator plays a vital role, shifting the focus from “who gets what” to “what do we stand for?” By framing the discussion around shared purpose, families begin to see taxes not just as an obligation, but as an opportunity to create something enduring.
 

A facilitator might ask questions such as, “If part of your estate could eliminate taxes and build a $3 million family fund, would you want your children and grandchildren to carry that forward together?” Or, “Would each child be willing to trade $500,000 of their inheritance for the chance to co-steward something bigger?” These kinds of prompts make the math real and the vision personal.

Once a family has agreed to redirect social capital, the tools to implement that decision are readily available:

●  Donor Advised Funds (DAFs): Cost nothing to set up, can be named in your will, and provide flexibility for heirs to decide over time.

●  Private Foundations: Offer more structure, visibility, and governance for families who want a formal framework.

●  Direct Bequests to Charities: Simple and immediate, though less adaptable for future generations.

●  Charitable Remainder Trusts: Allow income during life, with the remainder gifted later.

The specific tool matters less than the act of making the choice. A $1.5 million tax bill can either quietly leave the estate as an obligation or be transformed into a $3 million, family-directed legacy.

The Gift to the Next Generation

When philanthropy is woven into an estate plan, it becomes more than a tax strategy; it becomes a gift of connection, purpose, and shared responsibility. In our example, rather than each of three siblings inheriting $4 million, they would receive $3.5 million each alongside a $3 million family fund. In their 50s or 60s, they could gather annually to direct grants, with their children observing.
 
Those children would witness collaboration over conflict, hearing stories of the family’s values and sacrifices. They would see stewardship in action rather than entitlement. Here, wealth becomes more than money; it becomes a living legacy of connection, giving, and shared meaning.

Concluding Thoughts

Every Canadian family leaves a charitable gift, often by default, to the Canada Revenue Agency. Instead, let’s say that your kids inherit a $3 million family fund that they manage together. Your grandchildren will be able to see how they work together, share values, and make a difference. The difference lies in choice. At Beacon Family Office at Assante Financial Management Ltd., we help families ensure their wealth reflects their values and lasts a lifetime.

We welcome the opportunity to explore how your estate plan can support your family’s values and lasting impact. Feel free to schedule a conversation with us to get started.

DISCLAIMER:
 
Cory Gagnon is a Senior Wealth Advisor with Assante Financial Management Ltd. The opinions expressed are those of the author and not necessarily those of Assante Financial Management Ltd. Please contact him at 403 232 8378 or visit https://beaconfamilyoffice.com/ to discuss your particular circumstances prior to acting on the information above. This material is provided for general information, and the opinions expressed and information provided herein are subject to change without notice. Every effort has been made to compile this material from reliable sources; however, no warranty can be made as to its accuracy or completeness. Before acting on the information presented, please seek professional financial advice based on your personal circumstances.
Picture of ABOUT THE AUTHOR

ABOUT THE AUTHOR

As the Senior Wealth Advisor at Beacon Family Office at Assante, Cory Gagnon has supported successful family enterprises to preserve, protect and transition their wealth since 2011.

Cory’s personal objective as a Wealth Advisor is simple. He is committed to supporting families to take control of the areas of their lives that truly matter to them. This commitment revolves around using specific tools and strategies that enable families to take action with confidence which will support them through life’s critical transitions.
Picture of ABOUT THE AUTHOR

ABOUT THE AUTHOR

As the Senior Wealth Advisor at Beacon Family Office at Assante, Cory Gagnon has supported successful family enterprises to preserve, protect and transition their wealth since 2011.

Cory’s personal objective as a Wealth Advisor is simple. He is committed to supporting families to take control of the areas of their lives that truly matter to them. This commitment revolves around using specific tools and strategies that enable families to take action with confidence which will support them through life’s critical transitions.
Share this post:

Facebook
Twitter
LinkedIn

KEEP READING?

The Whole-Life Benefits of a Hobby You Love

Designing a Family Office That Serves Generations

The Whole-Life Benefits of a Hobby You Love

Designing a Family Office That Serves Generations

For most wealthy families, there comes a time when managing wealth informally becomes too complex. Multiple advisors, legal structures, tax considerations, and investment strategies converge, creating a need for the family to have a central hub to coordinate everything. That’s when the family office typically becomes involved.
 
Often, families think that their family office is doing its job if it is taking care of their investments. On the surface, that feels sufficient. Investment portfolios are monitored, performance reports are generated, and bills are paid. Effective stewardship across generations requires something more. The lasting impact of a family office arises from its support for the people and systems surrounding the capital, rather than focusing solely on the capital itself.

Where Families Often Begin

Upon selling a business or creating liquidity, families typically shift their immediate focus to investment management. Families want to preserve what they have built, and much of the attention goes toward protecting and growing capital. The family office is established to provide oversight, consolidate reporting, and ensure that managers align with the overall strategy.
 
While this stage is essential, it represents only one part of the overall journey. Any family recognizes that true success lies in thoughtful decision-making, fostering shared responsibility, and preparing the next generation to engage with confidence. These opportunities strengthen relationships, build trust, and ensure that the legacy you’ve created continues with clarity and purpose.

What Families Really Need

The family office shows its full value when it grows into a framework for continuity. It serves as a hub for organizing and making sense of complexity, aligning tax, legal, estate, and investment strategies with a shared vision.
 
It is also the setting where governance takes shape. Families require a clear understanding of who makes decisions, how to resolve disagreements, and how to maintain accountability. A well-designed office supports such needs by creating committees, codifying principles, and establishing processes that guide decisions over time.
 
Equally important, the family office provides a bridge between generations. Preparing the rising generation is a long process of education and involvement. When done well, heirs grow into responsible stewards, not just passive recipients

Where True Value Emerges

The families who make the most of their office see it as more than a service provider. They use it as a strategic hub that strengthens both relationships and balance sheets.
The real value is measured by the clarity it creates, the conflicts it prevents, and the confidence it provides to the family that decisions will be handled consistently. This stability is what allows wealth to remain purposeful and resilient across generations.

Concluding Thoughts

If you already have a family office, ask yourself whether it is simply handling investments or truly supporting the broader family system. If you are considering creating one, be clear about the role you want it to play. The design you choose today will impact not only financial results but also the sustainability of your family’s legacy in the future.

At Beacon Family Office at Assante Financial Management Ltd., we help families design offices that reflect their values, align their structures, and prepare their rising generations. If you are ready to explore how your office can serve as a framework for both capital and connection, I would welcome the opportunity to connect. Click here to start a conversation.

Picture of ABOUT THE AUTHOR

ABOUT THE AUTHOR

As the Senior Wealth Advisor at Beacon Family Office at Assante, Cory Gagnon has supported successful family enterprises to preserve, protect and transition their wealth since 2011.

Cory’s personal objective as a Wealth Advisor is simple. He is committed to supporting families to take control of the areas of their lives that truly matter to them. This commitment revolves around using specific tools and strategies that enable families to take action with confidence which will support them through life’s critical transitions.

Share this post:

Facebook
Twitter
LinkedIn

KEEP READING?

2025 Week 42

The Steward’s Playbook: How to Structure Wealth That Outlasts You

The Steward’s Playbook: How to Structure Wealth That Outlasts You

“The greatest use of life is to spend it for something that will outlast it.”
 
~ William James
 
Legacy does not occur by chance. It is built through structure, governance, and purpose.
With vision and resilience, you’ve built more than success; you’ve created opportunity and provided for others along the way. That foundation now gives you the freedom to look beyond immediate concerns and envision what will endure.
 
The questions ahead are no longer about chasing growth or solving the next urgent problem. They are about safeguarding what you’ve built, preparing those who will carry it forward, and ensuring your wealth reflects the values that matter most. These thoughtful considerations invite reflection and pave the way for lasting impact.

Turning Today’s Success Into Tomorrow’s Legacy

Running a company often calls for quick decisions and decisive action. Managing family wealth, however, is a longer journey, one that spans decades, invites many voices, and reflects a range of priorities. With the right structure in place, families can move from reacting to challenges toward building clarity, alignment, and confidence. Defined roles, intentional strategies, and shared purpose create not only stronger investments but also stronger relationships across generations.
 
In our recent Legacy Builders Podcast episode 53, Dennis Jaffe emphasized that “An entrepreneur is a certain personality type… The second generation, however, is different… it’s a group of people working together, and that’s not the reality of the entrepreneur. The next generation has to create a new way of working together, more collaborative and more team-oriented.” That shift underscores why families need frameworks that support collaboration, versus just individual decision-making.
 
I once met a family who had successfully transitioned from operating a business to managing significant liquidity. The family made decisions informally for years, lacking a clear process or defined roles. When differing priorities emerged among siblings, one focused on growth, another on preservation, and a third on philanthropy, discussions quickly turned tense. The absence of structure left them feeling uncertain, even though their financial resources were substantial.
 
If your business needed strategy and governance to succeed, why would your wealth deserve anything less? Families who address this early create clarity and alignment, giving future generations a stronger foundation to build upon.

The Pillars of Stewardship

Stewardship is about designing a system that endures. It brings clarity to decisions, consistency to how wealth is managed, and continuity across generations. At Beacon Family Office, I guide families through three interconnected pillars.
 
The first is structure. A strong foundation includes an Investment Policy Statement rooted in purpose, liquidity planning that anticipates needs and opportunities, ownership and trust arrangements that balance efficiency with continuity, and principles that define how decisions are made. The second is governance. Families benefit from clear roles, accountability, and agreed processes for areas such as philanthropy or private investing. The third is communication. The strongest frameworks thrive when everyone shares a common understanding. Families that thrive are intentional about meetings, conversations, and education, building a shared language that prepares the next generation to act as capable stewards rather than passive heirs.
 
In that same Legacy Builders Podcast conversation, Dennis Jaffe pointed out, “There’s governance of the business, and there’s governance of the family… we want to create responsible people… we have to educate and develop our rising generations… investing in the next generation is the way we want to use our wealth and resources.” In my work with families, I see the same truth: the earlier expectations are set and the rising generation is engaged, the stronger the family’s stewardship becomes.

Investment Strategy With Intention

By this stage, your wealth may include public markets, private equity, direct real estate, operating companies, and alternatives. Each element has a purpose, and when thoughtfully aligned, even complex portfolios can work seamlessly to support the family’s goals and long-term vision. Effective wealth strategy begins with purpose. Beyond returns, it’s worth reflecting on what you’re working toward, how investments align with your broader vision, and who will guide them in the years ahead. A thoughtfully structured portfolio supports liquidity needs, reflects your Investment Policy Statement, and remains clear to those entrusted with it in the future.

The Value of a Thoughtful Plan

Significant wealth offers opportunity, but its long-term impact depends on intentional stewardship. Without a guiding framework, even strong portfolios can face complexity, and transitions may feel uncertain for the next generation.
 
By embracing structure, governance, and open communication, families create clarity and alignment. Wealth then becomes more than capital; it becomes a tool to strengthen relationships, support shared goals, and empower future generations with confidence and purpose.

Concluding Thoughts

You have already proven yourself as a builder and leader. The next role is that of architect, creating systems that reflect your values and prepare your family for the responsibility of stewardship. This work ensures what you have built continues to serve its purpose.
 
It is worth asking how well your wealth is structured today, how prepared your family feels, and what kind of foundation you want to leave behind. The answers will define the legacy you pass forward.

If you want to discuss how to make your wealth clearer and more resilient, I'm delighted to help. The choices you make now will help safeguard what you have built and prepare your family to carry it on. Schedule a conversation today.

Picture of ABOUT THE AUTHOR

ABOUT THE AUTHOR

As the Senior Wealth Advisor at Beacon Family Office at Assante, Cory Gagnon has supported successful family enterprises to preserve, protect and transition their wealth since 2011.

Cory’s personal objective as a Wealth Advisor is simple. He is committed to supporting families to take control of the areas of their lives that truly matter to them. This commitment revolves around using specific tools and strategies that enable families to take action with confidence which will support them through life’s critical transitions.

Share this post:

Facebook
Twitter
LinkedIn

KEEP READING?

How Financial Planning Benefits Your Business

Positioning Wealth: Why Being Debt-Free Is Not the Finish Line

How Financial Planning Benefits Your Business

Positioning Wealth: Why Being Debt-Free Is Not the Finish Line

“Wealth is the ability to fully experience life.”

~ Henry David Thoreau

Imagine driving with your focus fixed on avoiding the ditch safely, but never really moving toward a destination. Many families approach wealth the same way: eliminating risk, avoiding debt, and keeping things simple. For years, I thought such an approach was the ultimate form of control. But I began to see that while resources were preserved, they weren’t being positioned to grow, create opportunities, or expand impact. True stewardship goes beyond safety; it’s about purpose, progress, and possibility.

When Safety is All that Matters

For many successful families and entrepreneurs, becoming debt-free feels like an achievement. It reflects discipline, patience, and a desire for control.

Yet maintaining control is not the same as expanding capability. In my years of working, I often meet families who have achieved remarkable results by avoiding unnecessary financial exposure, with no leverage, no outside investors, and no unpredictable obligations. That caution has protected them, but it can also limit the family’s capacity to pursue transformative opportunities.

You cannot scale a legacy by only avoiding losses. At some point, positioning wealth for growth becomes just as important as protecting it.

The Wealth Trap Few Talk About

One family I worked with had a net worth of $25 million and no liabilities. They self-funded every business expansion, real estate acquisition, and shareholder transition. When a unique opportunity arose to invest in a strategic partnership, they hesitated, not because they lacked capital, but because most of their wealth was tied up in long-term, illiquid assets.

By keeping all their capital unencumbered, they unintentionally reduced their flexibility when it was most crucial. Later, they told me, “We thought being debt-free gave us freedom, but it limited what we could do when the right opportunity came along.”

This pattern often stems from something deeper: fear of loss, difficult past experiences, or beliefs about money passed down through generations. Behavioural finance calls this loss aversion, the tendency to prioritize avoiding potential loss over pursuing potential gain. Even for families with substantial resources, this instinct can quietly influence strategic decisions.

The Strategic Use of Productive Debt

Not all debt is the same. Caution is warranted when debt is associated with depreciating assets, consumption, or emotional decisions. However, debt that is intentionally employed to acquire assets that are appreciating, generate income, or fund growth can be a potent instrument.

The structure matters as much as the decision itself. Terms, timing, and control determine whether leverage becomes a strategic advantage or an unnecessary constraint. Thoughtfully used, debt can release capital for reinvestment, create liquidity, and accelerate diversification.

As Warren Buffett stated in his Berkshire Hathaway 2017 Annual Letter (page 4), “It is insane to risk what you have and need in order to obtain what you don’t need.” The opposite is also true: it can be shortsighted to hold wealth in ways that prevent it from creating greater value for your family.

What a Healthy Net Worth Statement Shows

Families often think of wealth in terms of assets and liabilities alone. A more complete approach considers how those assets are positioned across generations, legal structures, and liquidity profiles.

In a well-structured family net worth statement, certain liabilities can be positioned as strategic instruments, tools to acquire appreciating assets, enhance liquidity, or facilitate generational transitions. The result is a portfolio that is more dynamic, diversified, and ready to adapt when opportunities arise.

Positioning Wealth for the Future

The most resilient families preserve wealth by positioning it. Strategic use of debt can:

● Unlock capital for reinvestment without forcing asset sales

● Provide flexibility across ownership and legal structures

● Support diversification and generational transitions

Wealth that remains static or overly concentrated in illiquid holdings can become vulnerable over time. Diversification and access to capital are what make a family enterprise resilient in changing conditions. 

Financial independence is not defined solely by being debt-free. It is the ability to act with clarity, take opportunities without jeopardizing stability, and shape a strategy that evolves with your family. Sometimes, carefully structured leverage becomes part of that freedom, enabling action without compromising liquidity, control, or long-term intent.

Concluding Thoughts

If your wealth strategy solely prioritizes safety, it could lead to preservation rather than progress. True wealth is more than protection; it’s positioning your resources to grow, create impact, and endure across generations. The families who thrive are those who approach risk with intention and align every decision with clarity and purpose.

If you’re wondering whether your current approach is creating momentum or simply holding position, it may be the right time to explore new possibilities. Feel free to book a call with us to start the conversation, and together, we can shape a plan that reflects your vision, supports your values, and provides confidence for years to come.

Picture of ABOUT THE AUTHOR

ABOUT THE AUTHOR

As the Senior Wealth Advisor at Beacon Family Office at Assante, Cory Gagnon has supported successful family enterprises to preserve, protect and transition their wealth since 2011.

Cory’s personal objective as a Wealth Advisor is simple. He is committed to supporting families to take control of the areas of their lives that truly matter to them. This commitment revolves around using specific tools and strategies that enable families to take action with confidence which will support them through life’s critical transitions.
DISCLAIMER

The case study mentioned in this presentation is based on actual scenarios, but names and identifying details have been changed to protect the privacy of individuals. This case study is provided for illustrative purposes only to provide an example of our process and methodology. The results portrayed are not representative of all of our clients’ experiences.

Picture of ABOUT THE AUTHOR

ABOUT THE AUTHOR

As the Senior Wealth Advisor at Beacon Family Office at Assante, Cory Gagnon has supported successful family enterprises to preserve, protect and transition their wealth since 2011.

Cory’s personal objective as a Wealth Advisor is simple. He is committed to supporting families to take control of the areas of their lives that truly matter to them. This commitment revolves around using specific tools and strategies that enable families to take action with confidence which will support them through life’s critical transitions.
DISCLAIMER

The case study mentioned in this presentation is based on actual scenarios, but names and identifying details have been changed to protect the privacy of individuals. This case study is provided for illustrative purposes only to provide an example of our process and methodology. The results portrayed are not representative of all of our clients’ experiences.

Share this post:

Facebook
Twitter
LinkedIn

KEEP READING?

Planning for Retirement as a Small Business Owner

Exit Planning: For Owners Who Aren’t Done Yet

Planning for Retirement as a Small Business Owner

Exit Planning: For Owners Who Aren’t Done Yet

“Someone’s sitting in the shade today because someone planted a tree a long time ago.”


~ Warren Buffett

Smart owners plan for their exit years in advance, even when retirement is not part of their immediate vision. Most business owners do not simply wake up one day ready to step away. The owners I work with are still building, innovating, and leading. They prioritize growth and impact over winding down.

At the same time, they understand that, either by design or by circumstance, there will be a moment when a transition happens. Exit planning is not a signal to slow down. It is a strategy to create options, reduce risk, and strengthen the business in ways that provide future freedom without giving up control today.

Planning the Next Chapter

Every owner will eventually transition from their business; the opportunity lies in choosing how and when. With thoughtful planning, you can design an exit that reflects your vision, protects what you’ve built, and provides freedom for what comes next. With preparation in place, you can meet life’s unexpected turns, such as death, disability, divorce, disagreement, and distress, with resilience. Rather than feeling caught off guard, you gain confidence in the security of your future, your family, and your business, regardless of the circumstances.

Building a company that can thrive without you takes time and intention. The process starts with identifying where the business depends on you personally, uncovering blind spots, and strengthening the value drivers that make it attractive to a future successor or buyer. For most owners, personal wealth is deeply tied to the business, which makes timing, preparation, and structure critical not only for maximizing value but also for protecting relationships and reputation.

Future-Proof Your Business

While retirement planning focuses on personal lifestyle, such as determining how much is enough and what life will look like after work, exit planning focuses on the business itself. It ensures continuity, reduces dependence on the founder, and prepares the next generation of leadership both inside the company and within the family. 

The questions are different:

● Who will lead when I step back?

● How do we align shareholder expectations?

● Will the family continue to own this business, or will it be sold to the most competitive bidder?

The two disciplines do overlap in areas such as tax strategy, estate planning, and wealth management, but the mindset is different. Retirement planning is about stepping away. Exit planning is about building a business and a legacy that can thrive without you. It is about making sure the structures, leadership, and vision are in place so that the enterprise continues to create value long after you have stepped back from daily operations.

The Value of Planning Ahead

Owners who plan early gain more than time; they gain control, confidence, and flexibility. With a thoughtful strategy in place, successors are prepared, transitions are smooth, and key decisions are made with clarity rather than urgency. Forward-looking planning turns potential challenges like health events, market shifts, or shareholder changes into opportunities to strengthen both the business and relationships. By reducing personal dependency and addressing future needs proactively, owners protect the value of their company while ensuring their legacy endures.

Our Approach to Exit Readiness

At the Beacon Family Office of Assante Financial Management Ltd., we begin with the owner versus the transaction. Together, we explore what “next” looks like personally, financially, and for your family. By preparing all three pillars, you gain the clarity, flexibility, and confidence to choose the right time, path, and legacy, turning your next chapter into an opportunity, not a decision by circumstance.

Concluding Thoughts

When owners begin exit planning early, they give themselves the ability to shape the future of both the business and the family on their terms. The process is less about a single transaction, and this includes building resilience, ensuring that the business can operate successfully without your constant involvement, and aligning leadership to facilitate transitions with clarity and purpose.

A well-prepared exit allows the business to thrive, keeps relationships strong, and gives the next generation confidence in their role. It reflects years of preparation, open communication, and strategic choices that expand options rather than limit them. Owners who take this path often find greater flexibility, stronger negotiating power, and peace of mind when the time for transition arrives.

Thinking about your next chapter? Let’s explore the possibilities, craft a strategy aligned with your values, and set your business and family up for lasting success. Schedule a conversation with us.

Picture of ABOUT THE AUTHOR

ABOUT THE AUTHOR

As the Senior Wealth Advisor at Beacon Family Office at Assante, Cory Gagnon has supported successful family enterprises to preserve, protect and transition their wealth since 2011.

Cory’s personal objective as a Wealth Advisor is simple. He is committed to supporting families to take control of the areas of their lives that truly matter to them. This commitment revolves around using specific tools and strategies that enable families to take action with confidence which will support them through life’s critical transitions.

Share this post:

Facebook
Twitter
LinkedIn

KEEP READING?

2025 Week 36

Opportunity in Unrest: A Timeless Investor’s Mindset

Opportunity in Unrest: A Timeless Investor’s Mindset

Imagine walking into your favourite boutique and discovering that the coveted, high-quality pieces you love are unexpectedly marked down by 40%. You’d expect excitement, perhaps even a line out the door.

But instead, people are hesitating to buy. Some walk away empty-handed, whispering, “Maybe it’s not the right time.”

While that reaction might sound absolutely absurd in retail, it’s surprisingly common in investing. When markets dip and long-term opportunities quietly become more attractive, many investors retreat. But those with a long view, the true stewards of wealth, often see something different: a chance to lean in with clarity and conviction.

“The time of maximum pessimism is the best time to buy.”

~ Sir John Templeton

A Familiar Play Just a Different Arena

In moments of volatility, the instinct is to act with the intention to protect. But for families with long-term capital, acting on emotion can often create unnecessary disruption.

True resilience comes from perspective, knowing that temporary noise doesn’t warrant permanent decisions. With a disciplined plan, families can navigate uncertainty with clarity, staying aligned with purpose rather than pulled by reaction.

Our Instincts Aren’t Built for Investing But Perspective Is

In moments of volatility, the instinct is to act with the intention to protect. But for families with long-term capital, acting on emotion can often create unnecessary disruption.

True resilience comes from perspective, knowing that temporary noise doesn’t warrant permanent decisions. With a disciplined plan, families can navigate uncertainty with clarity, staying aligned with purpose rather than pulled by reaction.

Culture Rewards Action: A Plan Rewards Alignment

People today often mistake urgency for progress. But when it comes to long-term wealth, it’s consistency, not constant reaction, that sustains results.

I recall a conversation in early 2020, during a period of steep market decline and widespread uncertainty. A client asked, “Should we sell and wait it out?” Instead of reacting, we revisited his plan, his cash flow needs, time horizon, and long-term goals. The answer was clear: there was no need to sell. So he didn’t. By year-end, not only had the market recovered, but also his strategy remained intact.

Another family had just completed the planned sale of a significant property. The timing wasn’t opportunistic; it was intentional. Proceeds were already allocated, liquidity needs covered, and a phased investment plan was ready. When volatility returned, we didn’t wait for the perfect moment. We implemented a structured dollar-cost averaging strategy, removing pressure, preserving clarity, and reinforcing discipline.

In both cases, confidence didn’t come from trying to outguess the market. It came from alignment with goals, with values, and with a well-crafted plan.

When strategy takes the lead, action takes on a purposeful nature, leading to a state of peace of mind.

The Market Moves; Your Portfolio Moves Differently

Market headlines often spotlight a single index like the S&P 500 as if it represents every investor’s reality. But for families like yours, wealth is built and preserved through far broader exposure.

Your portfolio likely spans public markets, private businesses, real estate, and structured strategies diversified across asset classes, sectors, and geographies. Each element responds differently to shifting economic cycles, offering unique sources of strength and opportunity.

Diversification doesn’t eliminate volatility, but it helps shape how you experience it. It instills resilience in your portfolio, stabilizes your decision-making during uncertain times, and strengthens your ability to stay on course anchored in purpose, not headlines.

Liquidity Brings Confidence Not Just Cash

One of the quiet strengths behind resilient, long-term investing is thoughtful liquidity. When near-term needs are intentionally accounted for through reserves, flexible structures, or accessible capital, there’s no pressure to sell high-quality assets in moments of uncertainty.

Well-designed portfolios honour this principle. Liquidity by design creates space not just for stability but for strategic decision-making. It enables families to act with clarity, remain patient through cycles, and stay aligned with their long-term vision.

Concluding Thoughts

Most of us wouldn’t hesitate to act on a meaningful opportunity in another part of life, yet investing often feels different, especially in times of uncertainty.

But for many successful wealth builders, confidence doesn’t just come from predicting markets. It stems from having a clear plan, thoughtful structure, and the flexibility to respond with intention versus urgency.

If you’ve been reflecting on how well your current approach supports long-term goals, particularly when it comes to liquidity, diversification, or resilience, we’d be glad to connect. Most of the time, a thoughtful conversation is the first step toward renewed clarity.

Picture of ABOUT THE AUTHOR

ABOUT THE AUTHOR

As the Senior Wealth Advisor at Beacon Family Office at Assante, Cory Gagnon has supported successful family enterprises to preserve, protect and transition their wealth since 2011.

Cory’s personal objective as a Wealth Advisor is simple. He is committed to supporting families to take control of the areas of their lives that truly matter to them. This commitment revolves around using specific tools and strategies that enable families to take action with confidence which will support them through life’s critical transitions.

Share this post:

Facebook
Twitter
LinkedIn

KEEP READING?